Here is a figure that stops most people mid-sip: the average equity release customer now unlocks more than £123,000 from their home. For a great many of us over 55, the house is worth more than every pension pot, ISA and savings account put together. And yet it is the asset we plan for least. property in retirement
That is the trouble with property in retirement. We spend thirty years paying the mortgage off, breathe a sigh of relief, and then treat the house as something that simply sits there quietly doing nothing. It doesn’t. Your home is a live financial decision every year you own it. Get the decisions right and it can fund your later years, cut your monthly outgoings and pass cleanly to your children. Get them wrong and it can quietly swallow tens of thousands of pounds in interest, care fees or unnecessary tax.
This guide walks through the seven mistakes I see most often with property in retirement — drawn from fifteen years of arranging mortgages and advising on
property in retirement for people in exactly this position. No jargon, no sales pitch, just what you actually need to know before you make a decision you can’t easily undo.
Mistake 1: Assuming you’re too old for a mortgage on your property in retirement
This is the single most expensive myth going. Someone rings their bank at 62, asks about borrowing against their property in retirement, gets told no, and concludes the whole market is closed to them. It isn’t — they’ve simply asked one lender out of ninety.
There is no legal maximum age for a UK mortgage. Each lender sets its own policy, and those policies vary enormously:
- High street banks: typically lend up to age 70–75 at application, with the loan repaid by 75–80.
- Specialist later life lenders: Livemore, Hodge, Suffolk Building Society and Family Building Society will often lend to 85 at application and 95 at the end of the term.
- Retirement Interest Only (RIO): no upper age limit at all. You pay the interest monthly; the capital is repaid when the house is sold, you move into care, or you die.
The right question is not “am I too old?” It’s “what income can I evidence, and how long do I want the loan to run?” A defined benefit pension, an annuity or a drawdown pot with a sustainability projection will all count. Lenders who specialise in property in retirement lean less on income multiples and more on whether your retirement income genuinely covers the payments.
A quick example. Margaret, 68, had £40,000 left on an interest-only mortgage that was due to end. Her bank said no and suggested she sell. A specialist lender offered a RIO at a sensible rate, her payments dropped, and she stayed in the house she’d lived in for thirty years. The difference was not her circumstances — it was which door she knocked on.
If your current deal is ending, read our guide to Remortgaging in Retirement and Getting a Mortgage After 55 before you speak to anyone.
Mistake 2: Never running the numbers on your property in retirement
Plenty of people keep the family home out of pure inertia, and never really decide what they want their property in retirement to do for them. That’s a perfectly valid choice — but make it a choice, not a default.
The real cost of staying
A four-bedroom house you no longer fill still costs you council tax, heating for empty rooms, insurance, and a roof that will eventually need doing. Add it up honestly over ten years and the figure often surprises people. Before you commit to staying put, think hard about keeping a house in retirement the downsides as well as the comforts.
The real cost of moving
Downsizing releases capital, but it is not free. Estate agent fees, conveyancing, removals and stamp duty on the new place can easily take £15,000 off what you expected to bank. Do the sum before you fall in love with a bungalow, because downsizing is the one property in retirement decision you cannot cheaply reverse.
A word of caution on retirement properties: purpose-built retirement flats carry service charges and often event fees, and they can be slow to resell. Plenty of people ask whether buying a retirement flat is a good investment, and honestly, that is the wrong question — these are homes to live in, not assets to trade. Investing in retirement property as a landlord is a different matter entirely, covered further down. For many people the security and community are worth it, but check the lease terms and ask the management company directly about recent resale times.
Mistake 3: Treating equity release as free money
Equity release has improved enormously. Plans are regulated, Equity Release Council members guarantee you’ll never owe more than the house is worth, and the market grew 11% in 2025 to £2.57 billion of lending. It is a legitimate way to turn property in retirement into spendable income.
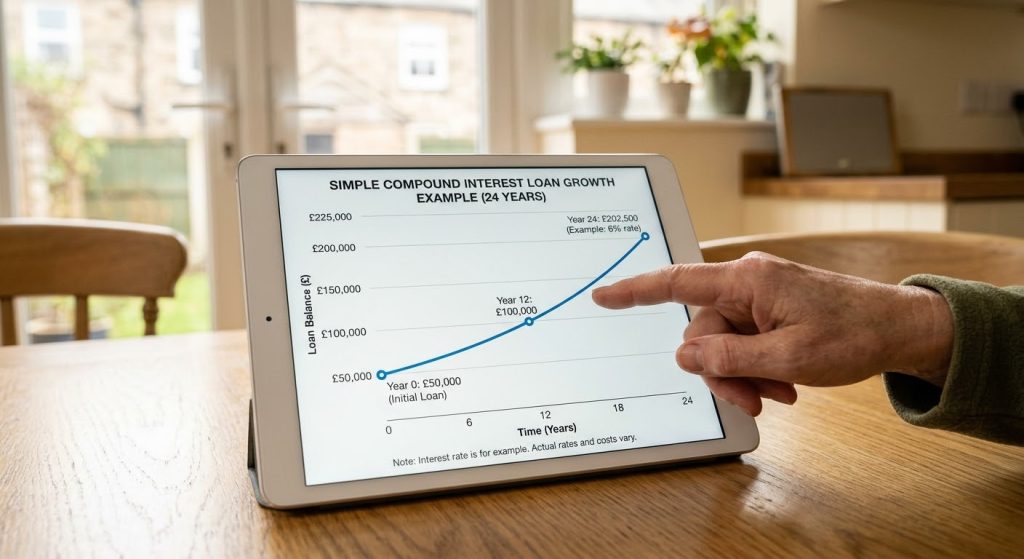
But the interest compounds, and that is where people come unstuck. Rates currently start at around 6.20% fixed for life, with the most expensive plans reaching 10.12%. Here’s what compounding actually means:
- Release £50,000 at 6% and make no repayments.
- After 12 years you owe roughly £100,000.
- After 24 years you owe roughly £200,000 — if the house hasn’t doubled in value, your children inherit very little.
That is not an argument against releasing money from your property in retirement. It is an argument for taking it in stages. A drawdown plan lets you take money as you need it, so interest only builds on what you’ve actually used. If you need £10,000 for a new boiler, don’t release £60,000 because it’s available.
Before you commit, MoneyHelper’s guide to equity release is a good impartial starting point, and Age UK on equity release sets out the alternatives worth ruling out first.
Three questions to ask before signing anything:
- Have I checked whether a RIO or standard later life mortgage would cost less?
- Am I taking the smallest amount that solves the problem?
- Does the plan let me make voluntary repayments without penalty?
Mistake 4: Becoming a landlord without doing the maths
Renting out a spare property, or keeping the old house when you move, looks like easy income. Sometimes it is. Often it is the least profitable thing you can do with property in retirement.
The things that catch people out are rarely the rent itself:
- The 5% stamp duty surcharge on an additional property.
- Mortgage interest relief restricted to a 20% tax credit, which pushes some pensioners into a higher band than they expected.
- Voids, repairs and agent fees — budget realistically, not optimistically.
- EPC and safety compliance, which lands on you, not the tenant.
Letting out property in retirement can still work, particularly if the property is owned outright. Our piece on Buy to Let in Retirement runs through the figures properly.
Mistake 5: Not understanding how property in retirement affects care home fees
Of all the property in retirement questions I get asked, this one causes the most anguish and attracts the most misinformation. Let’s be precise.
The capital limits
In England for 2026/27 the upper capital limit is £23,250 and the lower limit is £14,250. Above £23,250 you fund your own care in full. Between the two, you pay £1 a week for every £250 of capital above the lower limit. Wales uses a single £50,000 limit; Scotland uses £35,000 and provides free personal care for over-65s.
These figures are set each year in the government’s social care charging circular.
The cap that isn’t coming
You may have read about an £86,000 lifetime cap on care costs. It was cancelled in July 2024 — not delayed, cancelled. Plenty of articles online still describe it as forthcoming. Plan on the basis that there is currently no cap.
Will you have to sell the house?
Usually not during your lifetime. Your home is disregarded for the first 12 weeks of permanent residential care. After that you can enter a Deferred Payment Agreement, where the council pays the fees and places a charge on the property, repaid when it’s eventually sold. Interest applies — the Department of Health and Social Care rate from 1 January 2026 is 4.75% APR, compounded.
For context on what you might be funding: self-funders typically pay around £1,300 a week for residential care and £1,600 for nursing care, often £200 a week more than the council pays for the identical room.
A word on deliberate deprivation. Signing the house over to the children to avoid fees rarely works. Councils can look back indefinitely and treat the asset as though you still owned it. Worse, you lose control of your own home. Please take proper advice on your property in retirement before going anywhere near this.
See our detailed guides to Care Home Fees and the Disabled Facilities Grant, which can fund adaptations that keep you at home for longer.
Mistake 6: Leaving the paperwork until it’s urgent
Two documents do more to protect your property in retirement than anything else you can do, and both must be sorted while you have capacity.
- A Lasting Power of Attorney. Without one, if you lose capacity nobody can sell, remortgage or even manage the house without a Court of Protection application — which is slow and costly.
- An up-to-date will. Particularly vital if you’ve remarried, own the property as tenants in common, or want to protect a share for children from a first marriage.
How you legally own the property matters more than most people realise, and it is the detail that decides where property in retirement finally ends up. Joint tenants means the survivor automatically inherits everything. Tenants in common means each share passes under the respective will — which is the structure used to protect children’s inheritance after a remarriage.
Our guide to Making a Will covers the essentials.
Mistake 7: Forgetting the inheritance tax angle on your property in retirement
The main residence nil-rate band can add up to £175,000 per person to the standard £325,000 allowance, when a home is left to direct descendants. For a married couple that can mean up to £1 million passing free of inheritance tax.
But it tapers away on estates above £2 million, and it only applies to children, grandchildren and other direct descendants. If you’re leaving the house to a niece, a friend or a charity, the sums are different. And from April 2027, unused pension pots are due to fall within estates for inheritance tax — which changes the old advice about spending property wealth before pension wealth.
If your estate is anywhere near these thresholds, an hour with a solicitor is cheap insurance against losing a slice of your property in retirement to tax.
Frequently asked questions
What is the maximum age for a mortgage in the UK?
There is no legal maximum age for borrowing against property in retirement. High street lenders generally cap borrowing at 70–75 at application and 75–80 at the end of the term, but specialist later life lenders go to 85 at application and 95 at the end of the term. Retirement Interest Only mortgages have no upper age limit, and equity release is available from 55.
Will I have to sell my house to pay for care?
Usually not while you are alive. Your home is ignored for the first 12 weeks of permanent residential care, and after that a Deferred Payment Agreement lets the council cover the fees against a charge on the property, repaid when it is sold. Interest is charged at 4.75% APR from January 2026.
Is equity release a good idea for pensioners?
It can be, if you take the minimum you need and understand that interest compounds. At around 6.20% a balance roughly doubles every twelve years. Always compare it against a Retirement Interest Only mortgage on your property in retirement first, and use an Equity Release Council member so the no-negative-equity guarantee applies.
Can I rent out property in retirement?
Yes. There is no age limit on letting out property in retirement, though buy to let mortgages have their own age caps. Factor in the 5% stamp duty surcharge on additional properties, restricted mortgage interest relief, void periods and compliance costs before assuming the rent is profit.
The bottom line
Property in retirement is not a passive asset. Every year you own it you are making decisions — about borrowing, about staying or moving, about what happens if your health changes — whether or not you realise you’re making them.
The seven mistakes above have one thing in common. Every one comes from acting on assumptions about property in retirement rather than checking the facts: assuming you’re too old to borrow, assuming equity release is the only option, assuming the care cap still exists, assuming the will you wrote in 1998 still does what you want.
So here’s the practical takeaway. Pick one item from this list this week — just one. Dig out your title deeds and check whether you’re joint tenants or tenants in common. Or find out when your mortgage term actually ends. Or ring a whole-of-market broker and ask what’s genuinely available to someone your age. Small, specific actions beat a vague intention to sort it all out one day.
And if this has raised questions, have a look through our Housing & Care and Legal & Wills sections — there’s a detailed guide for almost every decision mentioned here. Getting property in retirement right is rarely about clever tricks. It’s about knowing the rules before they apply to you.
This article is general information, not regulated financial advice. Mortgage, equity release and care funding decisions depend on your personal circumstances — always speak to a qualified adviser before acting. Your home may be repossessed if you do not keep up repayments on a mortgage secured against it.